Whitbread raises £300m in new debt and says its borrowing costs will rise
The Premier Inn owner priced a seven-year bond and expects its average cost of debt to climb once a 2031 green bond matures.
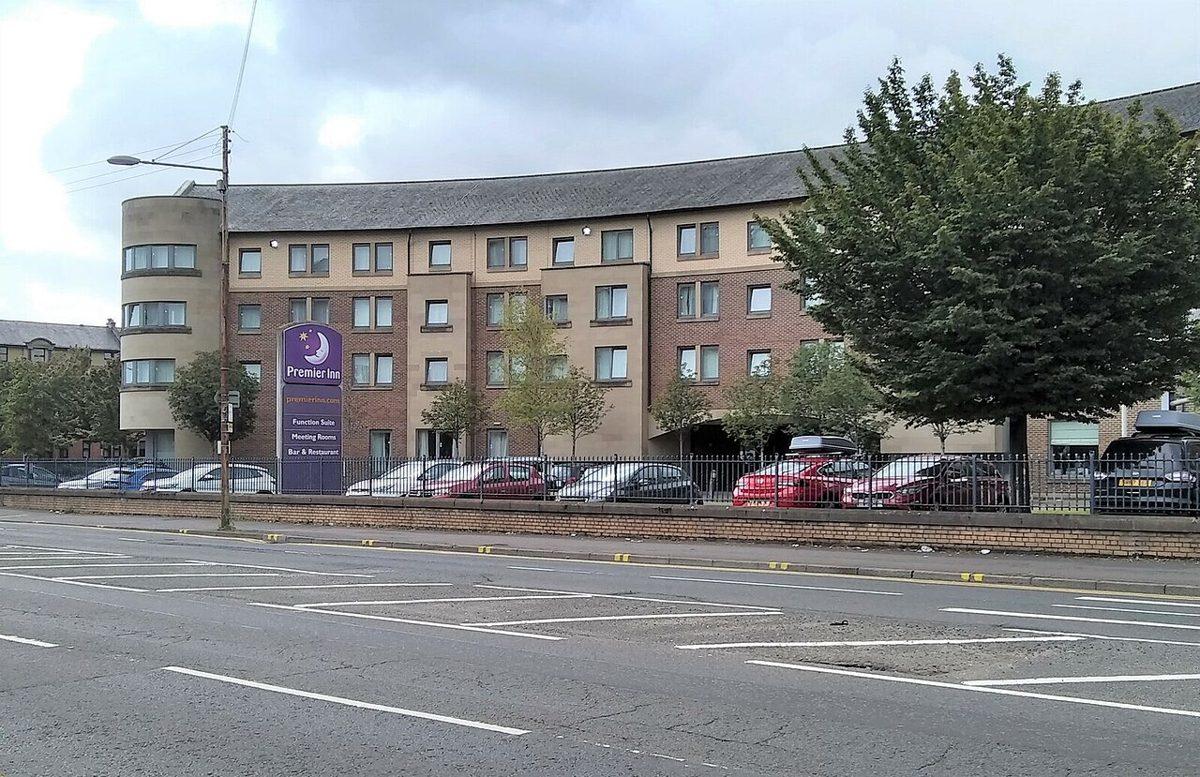
Whitbread, the owner of Premier Inn, has launched and priced a £300m seven-year bond, according to a stock market announcement on 12 November.
The terms: the bond was priced at 173 basis points over the reference gilt rate. It is unsecured, carries no financial covenants and is expected to be rated BBB- by Fitch, in line with the group's current credit rating. Admission to trading on the London Stock Exchange is expected on or about 19 November.
The hedge: alongside the pricing, Whitbread has entered £100m of interest rate swaps to turn part of the fixed coupon into a floating rate linked to SONIA.
The cost of money: after this issue, the group's weighted average cost of debt will be about 3.8%. Whitbread expects that to rise to about 4.5% once its £300m 2031 green bond matures.
What the money is for: general corporate purposes, including refinancing existing debt.
Why it matters: even an investment-grade operator with no covenants on the new paper is guiding to dearer borrowing over time. If your own facilities roll over in the next few years, it is worth modelling refinancing at current rates rather than the ones you signed up to, and testing what that does to the returns on your next round of capex.
Source: Whitbread (London Stock Exchange RNS) (opens in a new tab)
- whitbread
- premier-inn
- debt
- finance
- hotels